

Securities Regulation Daily Wrap Up, BLOCKCHAIN—C.D. Cal.: Plaintiffs get another chance to show that Bored Ape digital assets are securities, (Oct 6, 2025)
Law Firms Mentioned:Scott and Scott LLP | Skadden Arps Slate Meagher and Flom LLP
Organizations Mentioned:Scott + Scott, LLP | Skadden Arps | Yuga Labs, Inc.
By R. Jason Howard, J.D.
Despite satisfying a sub-prong of the Howey test, the plaintiffs failed to allege that any, some, or all of the defendants’ digital assets were a security.
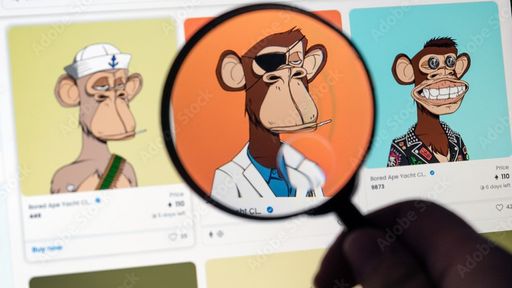
The Central District of California has dismissed a second amended complaint brought against Yuga Labs, Inc., the creator of non-fungible tokens or “NFT” collections known as the Bored Ape Yacht Club, the Mutant Ape Yacht Club, and the Bored Ape Kennel Club, after finding that the plaintiffs failed to adequately allege that Yuga’s digital assets were securities (Adonis Real v. Yuga Labs, Inc., No. 2:22-cv-08909-FMO-BFM (C.D. Cal. Sept. 30, 2025)).
Blockchains and NFTs. “Blockchains” are decentralized digital ledgers that can permanently store information about transactions. NFTs are software code associated with separate, often digital, content. The code operates as a unique digital watermark on an otherwise replicable digital file, such as an image. The value of a particular Yuga NFT was tied to the relative rarity of its unique traits and accessories.
Claims. The plaintiffs asserted federal law claims in addition to California and Florida state law claims individually and on behalf of a putative class of persons who purchased Yuga’s products and were subsequently damaged thereby.
Question. The court stated that the question was whether the plaintiffs’ second amended complaint adequately alleged that Yuga assets were securities. Under the Securities Acts, the term security includes the commonly known documents traded for speculation or investment, such as an investment contract.
The court cited to SEC v. W.J. Howey Co. (Howey), 328 U.S. 293, 297, 66 S. Ct. 1100, 1102 (1946) in explaining that “although the Securities Acts do not define ‘investment contracts,’ courts, including the Supreme Court, have taken the term to mean a contract or scheme for the placing of capital or laying out of money in a way intended to secure income or profit from its employment.” The court then noted that the Ninth Circuit has distilled Howey’s definition of an investment contract into a three-part test requiring: (1) an investment of money, (2) in a common enterprise, (3) with an expectation of profits produced by the efforts of others.
The court addressed each prong of the Howey test and found that the plaintiffs failed to adequately allege that Yuga’s digital assets were offered as investments as opposed to being for personal consumption and failed to adequately allege either horizontal or vertical commonality in support of the common enterprise prong of the Howey test.
In discussing the third prong of the Howey test, the court explained that an expectation of profits produced by the efforts of others involves two distinct concepts: whether a transaction involves any expectation of profit, and whether expected profits are the product of the efforts of a person other than the investor. Here, the court stated that “because the third Howey prong emphasizes purchaser expectations rather than the character of the instruments,” it looked to plaintiffs’ allegations through that lens.
In doing that, the court found that it was not objectionably reasonable for the plaintiffs to base their expectation of speculative profit on statements made by Yuga Labs concerning its products inherent, long-term, and intrinsic value because, “statements about a product’s inherent or intrinsic value are not necessarily statements about profit.”
Turing to whether the expected profits were the product of the efforts of a person other than the investor, the court explained that the ‘efforts of others’ analysis “looks to whether the efforts made by those other than the investor are the undeniably significant ones, those essential managerial efforts which affect the failure or success of the enterprise.” Here, the court explained that to the extent that plaintiffs reasonably expected any profits, there were no allegations that suggested that such profits would come from plaintiffs’ own efforts and pointed to Yuga’s statements that “the value of the collections was a top priority and was tied to defendants’ own efforts in the form of ‘Roadmap Activations.’”
The court reasoned that while the precise nature of those “Roadmap Activations” was not clear, it appeared that the plaintiffs adequately alleged that defendants, not plaintiffs or other investors, would be responsible for developing and implementing the “Roadmap Activations” upon which the products’ future value would depend. Despite satisfying that sub-prong, the plaintiffs failed to satisfy the other prongs of the Howey test and, therefore, failed to allege that any, some, or all of the defendants’ digital assets were a security.
Conclusion. The court dismissed the second amended complaint and granted leave to amend with instructions that the third amended complaint be filed by October 10, 2025, and not exceed 200 pages.
The case is No. 2:22-cv-08909-FOM-BFM.
Judge: Olguin, F.
Attorneys: John T. Jasnoch (Scott and Scott LLP) for Adonis Real. Alexander C. Drylewski (Skadden Arps Slate Meagher and Flom LLP) for Yuga Labs, Inc.
Companies: Yuga Labs, Inc.
MainStory: TopStory Blockchain FraudManipulation InvestorEducation CaliforniaNews FloridaNews